


CFO Message (Financial Strategy)
Leveraging our strong financial base to create a virtuous cycle of growth investment, greater capital efficiency, and shareholder returns, we aim to sustainably enhance corporate value and achieve our goal of becoming a 200-billion-yen company by fiscal year 2030.
- Review of the Fiscal Year 2025: Strengthening Our Earnings Base amid Uncertainty
- Initiatives to Improve ROE: Advancing Profitability, Asset Efficiency, and Capital Policy in an Integrated Manner
- Shareholder Returns: Enhancing Returns while Balancing Growth Investment
- Enhancing Management Transparency through Dialogue with Investors and Shareholders
- Toward Becoming a 200-Billion-Yen Company by Fiscal Year 2030
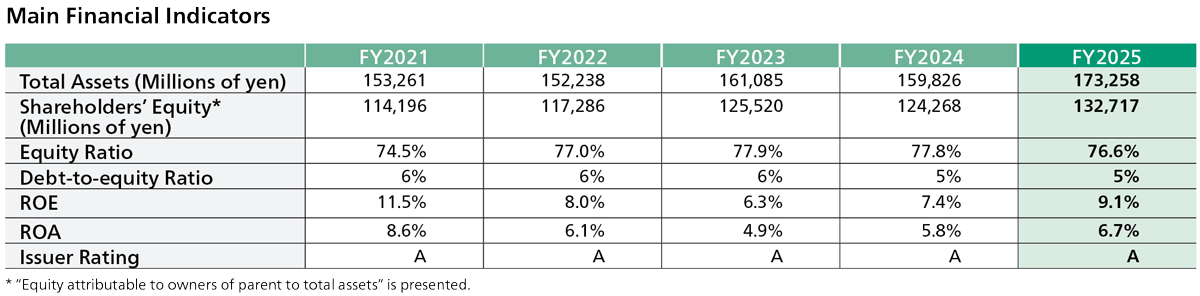
GLP2026, our Global Long-term Management Plan launched in April 2024, is an important milestone toward becoming a 200-billion-yen company by fiscal year 2030. In fiscal year 2025, the second year of the plan, we leveraged the Anritsu Group’s collective capabilities and strong financial base to deliver growth in both revenue and profit and improve capital efficiency despite continued uncertainty in the external environment. Consolidated revenue was 117.5 billion yen, operating profit 14.8 billion yen, and profit 11.7 billion yen, while ROE improved to 9.1%. We also generated 17.9 billion yen in cash flow from operating activities, executed growth investments including bringing DEWETRON into the Group as a consolidated subsidiary, and maintained a sound financial position with an equity ratio of 76.6%. Looking ahead, our priority is not only to achieve the targets for the final year of GLP2026 but also to create a virtuous cycle of growth investment, capital efficiency, and shareholder returns on the path to becoming a 200-billion-yen company by fiscal year 2030. We will continue transforming our business portfolio and strengthening our earnings base to sustainably enhance corporate value.
Review of the Fiscal Year 2025: Strengthening Our Earnings Base amid Uncertainty
Fiscal year 2025 was marked by a highly uncertain business environment, reflecting the continued transition period between 5G and 6G, U.S. tariff policy, and investment adjustments in the EV market. At the same time, the spread of generative AI is accelerating investment in data centers, which we view as a medium- to long-term growth opportunity.
In the Test and Measurement Business, while a full-fledged recovery in mobile-related investment did not materialize, data center-related solutions grew in importance as a new growth driver. Sales of general-purpose test instruments also increased as we strengthened our initiatives in industrial measurement, further diversifying revenue sources within the Test and Measurement Company.
At the Group level, the PQA Business made a significant contribution not only to revenue growth but also to improved profitability, supported by rising demand for more sophisticated quality assurance and for automation and labor-saving solutions in the food and pharmaceutical markets. The PQA Business serves a customer base distinct from the Test and Measurement Business and benefits from relatively stable demand, steadily strengthening its position as a key earnings pillar for the Group.
The Environmental Measurement Business and Sensing & Devices Business also grew steadily. In Environmental Measurement, bringing DEWETRON into the Group strengthened the foundation for global expansion and broader business development.
As a result, the Anritsu Group achieved growth in both revenue and profit even without a full-fledged recovery in the mobile-related market. This demonstrates the steady progress we are making in strengthening the resilience of our earnings base as we evolve from a business structure centered on mobile communications test and measurement to a portfolio with multiple growth drivers, including data center-related solutions, industrial measurement, PQA, environmental measurement, and sensing and devices.
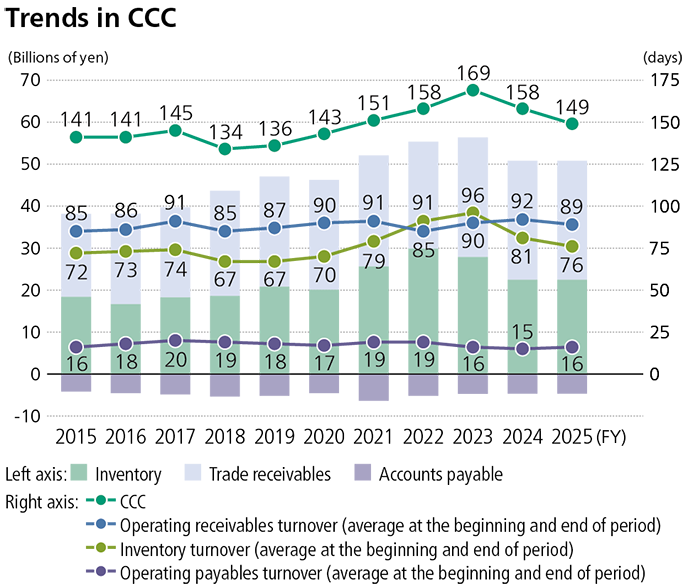
On the financial front, we optimized inventories and improved sales efficiency while steadily generating cash flow from operating activities. We also maintained a sound financial base while continuing growth investments. Going forward, we will accelerate PMI and the realization of synergies to improve returns on invested capital.
Initiatives to Improve ROE: Advancing Profitability, Asset Efficiency, and Capital Policy in an Integrated Manner
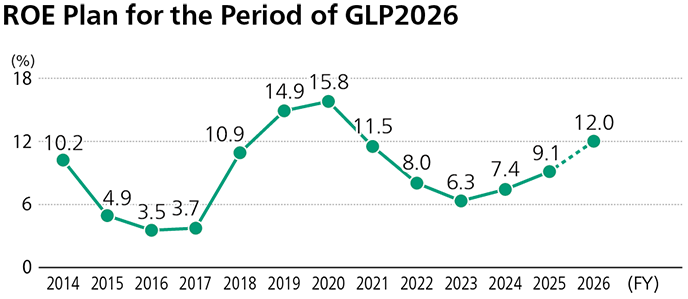
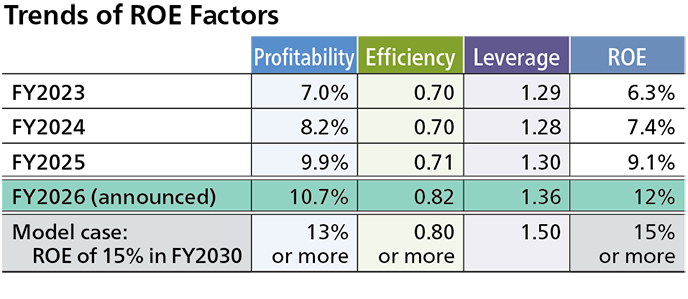
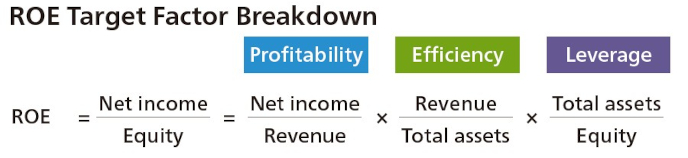
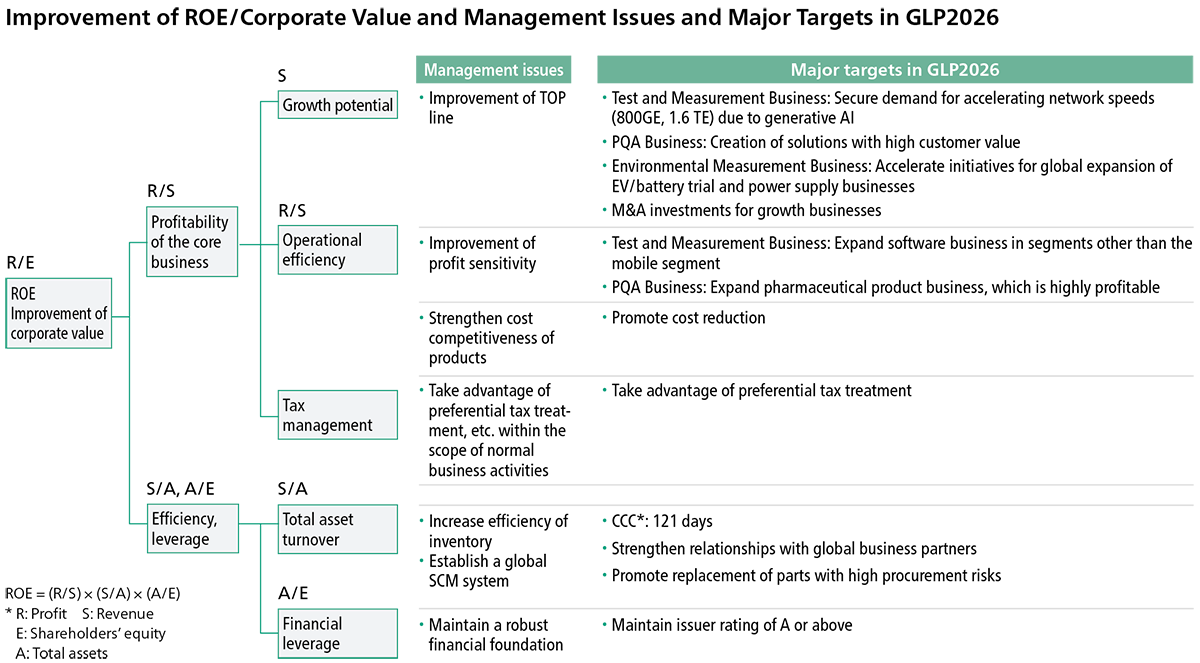
We regard ROE as a key metric for enhancing corporate value. ROE for fiscal year 2025 was 9.1%, above our estimated cost of equity of 7%. To achieve our ROE target of 12% for the final year of GLP2026 and our longer-term goal of 15% by fiscal year 2030, however, we need to improve profitability and asset efficiency while further enhancing our capital policy, with all three pursued in tandem.
To improve profitability, we will capture demand in the Test & Measurement Business related to 6G and IOWN, as well as data center demand driven by generative AI, while accelerating profit growth across the business portfolio through stronger earnings in the PQA Business, synergy creation with DEWETRON, and growth in the Environmental Measurement Business and Sensing & Devices Business.
To improve asset efficiency, we will improve CCC and optimize inventories while allocating management resources using business-specific ROIC. For M&A and capital investment, we will apply a consistent cost-of-capital discipline from the investment decision through post-investment monitoring and select investments that contribute to enhancing corporate value.
With respect to capital policy, we will pursue the optimal balance between growth investment and shareholder returns while maintaining our strong financial base and issuer rating of “A” to support a sustained improvement in ROE.
Cash Flow Management: Generating the Cash to Fund Growth
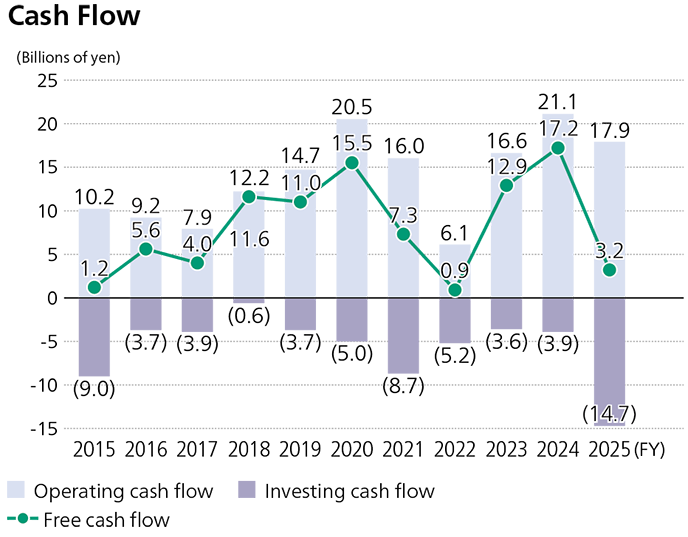
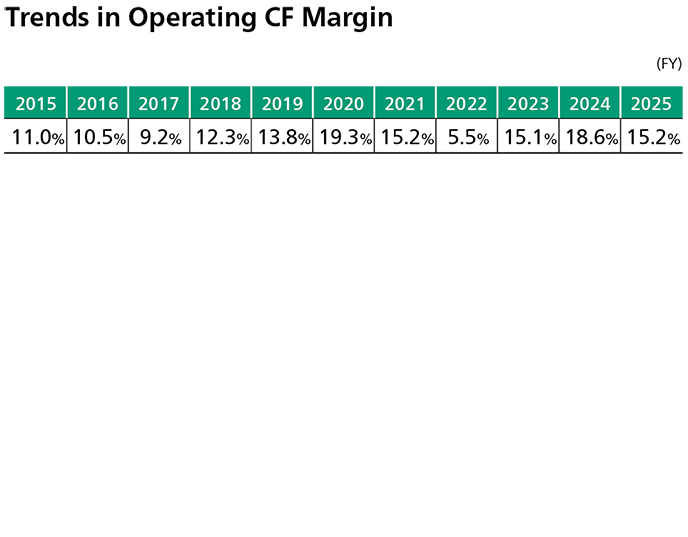
One of my highest priorities as CFO is strengthening our ability to generate the cash needed for growth. Sustainable enhancement of corporate value depends on our ability to generate operating cash flow consistently by managing not only revenue growth but also profitability, inventories, trade receivables, trade payables, and investment efficiency in an integrated manner.
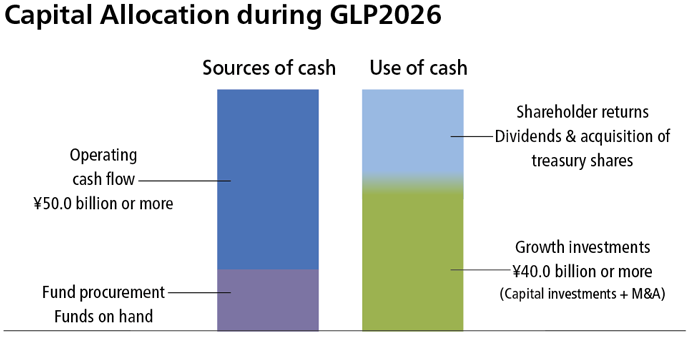
In fiscal year 2025, we generated 17.9 billion yen in cash flow from operating activities. At the same time, cash flow from investing activities was a 14.7 billion yen outflow as we executed growth investments. These investments are intended to strengthen the business foundation for becoming a 200-billion-yen company by fiscal year 2030. We are now entering the stage of translating those investments into revenue growth, higher profit margins, and improved ROE.
We will continue to manage development ROI, business-specific ROIC, CCC, and operating cash flow in an integrated manner, balancing growth investment with financial discipline. This will enable us to capture medium- to long-term growth opportunities while maintaining a resilient financial position that can withstand short-term earnings volatility.
Capital Allocation: Linking Growth Investment to Higher Corporate Value
Under GLP2026, we plan to allocate more than 40.0 billion yen to growth investments. Our priority areas are 6G and the three new business areas: Industrial Measurement, EV/Battery, and Pharmaceutical. We will combine M&A, capital investment, R&D, and human capital investment to develop new pillars of growth.
Welcoming DEWETRON into the Group in fiscal year 2025 was an important step in accelerating the global expansion of the Environmental Measurement Business. We will combine DEWETRON’s power measurement and data acquisition technologies with the Anritsu Group’s capabilities in EV/battery testing and social infrastructure monitoring and our global sales network to realize synergies as quickly as possible.
The rapid spread of generative AI is also driving higher-speed, higher-capacity networks in data centers. As a result, evaluation requirements for optical interconnects, PCIe, semiconductors, and electronic components will continue to become more sophisticated. By leveraging the advanced “testing” technologies we have developed in communications test and measurement, we will capture this growth opportunity by helping customers accelerate development and ensure quality.
Investment in human capital is also indispensable to enhancing corporate value over the medium to long term. We will develop and recruit technical talent for our growth areas, global business leaders, and specialists in areas such as M&A, PMI, and FP&A who support the management foundation, thereby building a sustainable competitive advantage.
Shareholder Returns: Enhancing Returns while Balancing Growth Investment
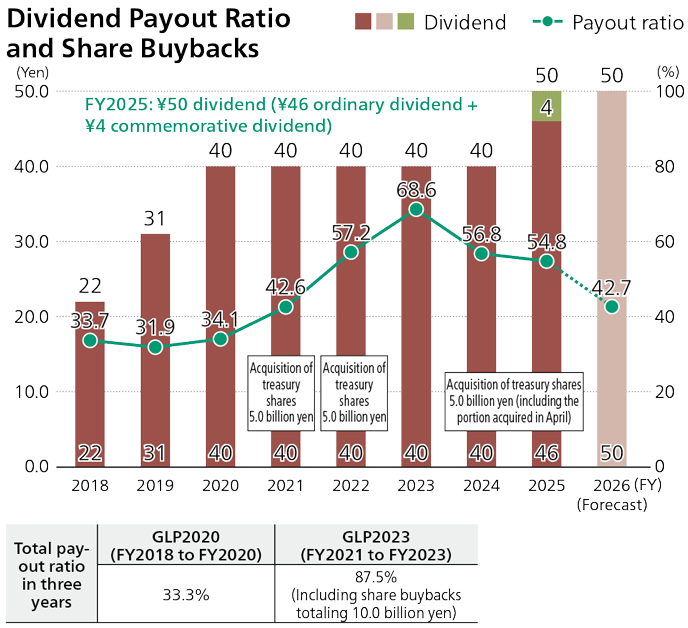
Our basic policy on shareholder returns is to target a consolidated dividend payout ratio of 50% or more and raise DOE in line with profit growth.
The annual dividend for fiscal year 2025 was 50 yen per share, with the year-end dividend including a 4 yen commemorative dividend marking the 130th anniversary of Anritsu’s founding. This reflects both our gratitude for shareholders’ longstanding support and our confidence in the strength of our financial base and future growth.
At the same time, simply increasing shareholder returns is not, in itself, the source of sustainable corporate value creation. We believe the most sustainable way to increase shareholder value is to generate profit growth through investment in 6G, new growth areas, global expansion, human capital, and R&D, and then return the benefits of that growth to shareholders.
We will also make flexible decisions on share buybacks, taking comprehensive account of our financial position, progress on growth investments, share price levels, and capital efficiency.
Enhancing Management Transparency through Dialogue with Investors and Shareholders
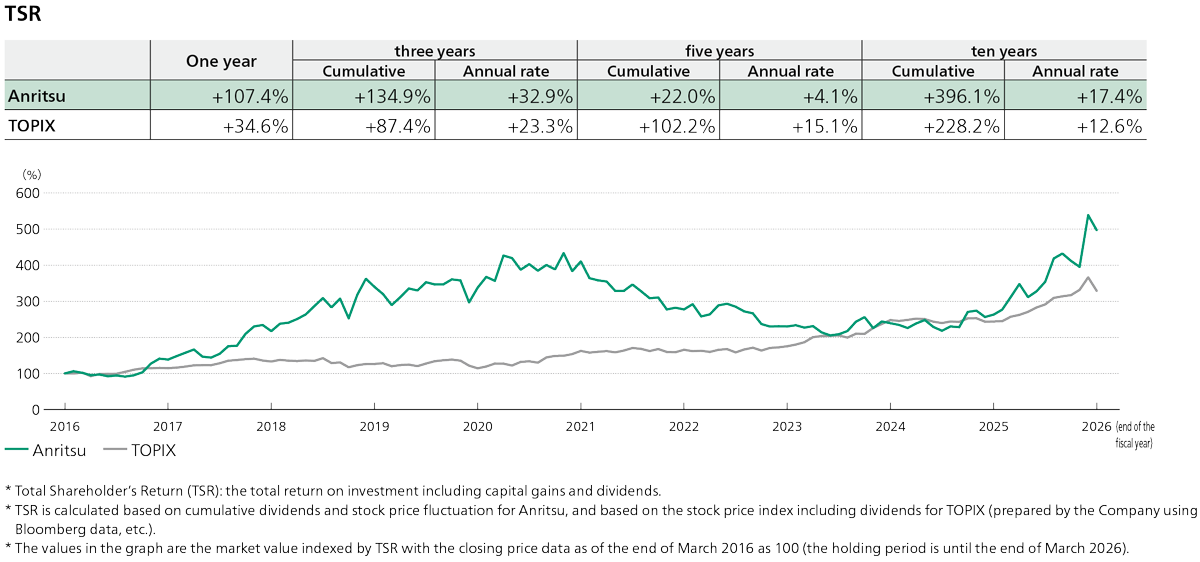
Expectations from capital markets continue to rise. Investors and shareholders are focusing on an ever broader range of issues, including ROE, ROIC, cost of capital, PBR, TSR, cross-shareholdings, human capital, climate change, and governance.
We view these not simply as disclosure items, but as important topics for dialogue that enhance management quality.
As CFO, I will use feedback received through dialogue with shareholders and investors to improve management strategy, financial strategy, capital policy, and disclosure. With the IR Department reporting directly to the CFO, we will further enhance management transparency and communicate the Anritsu Group’s medium- to long-term value creation story more clearly by presenting financial and non-financial information in an integrated manner.
Toward Becoming a 200-Billion-Yen Company by Fiscal Year 2030
For 130 years, Anritsu has evolved its businesses in step with changes in society and advances in technology. Going forward, as a company that goes beyond “testing,” beyond limits, and contributes to a sustainable future, we will create new value in growth areas such as 6G, next-generation networks supporting generative AI, safety and security in food and pharmaceuticals, EV/battery, industrial measurement, and more advanced social infrastructure.
My mission as CFO is not merely to protect our strong financial base, but to put that strength to work for growth, enhance capital efficiency, and translate it into sustainable increases in corporate value.
As we move toward the final year of GLP2026, we will steadily realize the returns from our growth investments, achieve ROE of 12%, and put ourselves firmly on track to achieve ROE of 15% and become a 200-billion-yen company by fiscal year 2030.
To meet the expectations of all stakeholders, including shareholders and investors, the Anritsu Group will further strengthen its cash-generating capabilities, financial discipline, capital efficiency, and transparent dialogue, and create sustainable corporate value by consistently generating returns above the cost of capital.
 Your Privacy Choices
Copyright 2026